Who Should Register for Income Tax Self-Assessment?
Company Director

Self-Assessment for directors is required if you receive dividends or any other untaxed income in addition to your director’s salary.
A common reason for small owner managed company directors to register is that they will often have a director’s loan account with the company, and this can have several income tax consequences which are dealt with through self-assessment.
Partner

A partnership is a business which is owned and managed by more than one person. Each partner is jointly responsible for all aspects of the business and will share the profits.
Partnerships have a requirement to complete and submit a self-assessment tax return to HM Revenue and Customs (HMRC).
In addition to the partnership registering for self-assessment, each partner must also register for self-assessment.
Sole Trader

If income from self-employment is in excess of £1,000 (known as the trading allowance), then registration as a sole trader is required.
Registration is also beneficial in order to prove self-employment status for the purposes of applying for personal loans and for certain state benefits such as tax-free childcare.
The trading allowance will be increased to £3,000 from tax year 2027/28.
Have Savings Income

If an individual who is a basic rate taxpayer has savings income of more than £1,000 then they should register.
High-rate taxpayers are required to register if savings income is greater than £500.
Interest income would include, to name a few, interest earned from bank or building society accounts, government or company bonds, trust funds, unit trusts, life annuity payments, savings or credit union accounts.
Interest income from tax free ISAs does not need to be included in the self-assessment tax return.
Have Investments Income

If an individual has shares in a company, they may receive dividends. If dividend income is over £500, registration is required.
Dividends would also include those from abroad (foreign dividends).
Receive Foreign Income

If you are resident and/or domiciled in the UK for tax purposes, you are taxable here on your worldwide income.
Overseas income includes interest, dividends, rental income, state pensions and personal pensions to name a few.
Receive Child Benefit

The ‘High Income Child Benefit Charge’ (HICBC) is a tax charge which applies to anyone with an income over £60,000, who claims Child Benefit or whose partner claims it. If you or your partner earns over £60,000, you must register for self-assessment.
You can ask HMRC to opt you out of the child benefit scheme and this would no longer require a self-assessment submission to be made every year.
Have Disposed of Assets

If you have disposed of assets and made a gain more than £3,000 (this is net of any losses made on disposal), you should register for self-assessment.
Even if your total gain is less than £3,000 (the capital gains allowance), you will still have to report to HMRC via self-assessment if the total proceeds from the disposals totalled £50,000 or more and you are already registered for self-assessment.
Want To Claim Employment Expenses

If you are an employee and have incurred work expenses of at least £2,500 which your employer was allowed to reimburse you tax free, but they have not done so, then you can claim the tax relief via self-assessment.
If the total non-reimbursed expenses were under £2,500, a P87 form can be filled out and sent to HMRC.
Landlord

You should register if your rental income is over £1,000 before any allowable expenses or is over £2,500 after allowable expenses.
HMRC may be able to collect tax on any profit you make from renting through your tax code if it was more than £1,000 but below £2,500. HMRC would have to be contacted by the individual to ask for this amendment otherwise self-assessment registration is required.
What Information Is Needed To Complete A Tax Return?
You need to keep records of your taxable income and gains to be able to complete the tax return. You do not have to send original documents to HMRC, but if HMRC ask questions later, you might need them as back-up and to show you took reasonable care to get your return right. Records must be kept for 5 years from the filing deadline for the return.
What Are The Key Self-Assessment Deadlines?

A tax year begins on the 6th April of one year until the 5th April of the of next year.

This is the date after the end of the tax year for which registration is required.
Paper tax returns must be submitted after the end of the tax year by this date.
Online tax returns must be filed after the end of the tax year by this date.
Tax must be paid by the return filing date.
If you have paid 80% or less of your tax bill at source for the tax year covered by the return or your tax bill is over £1,000 you will have to make payments on account for the current tax year. Two payments on account will have to be made which each equal half of the self assessment tax bill for the return filed. Payment 1 will be due on the filing date and payment 2 will be due by 31 July after the end of the current tax year.
What Are The Penalties for Late Filing?

What Are The Penalties for Late Payment?

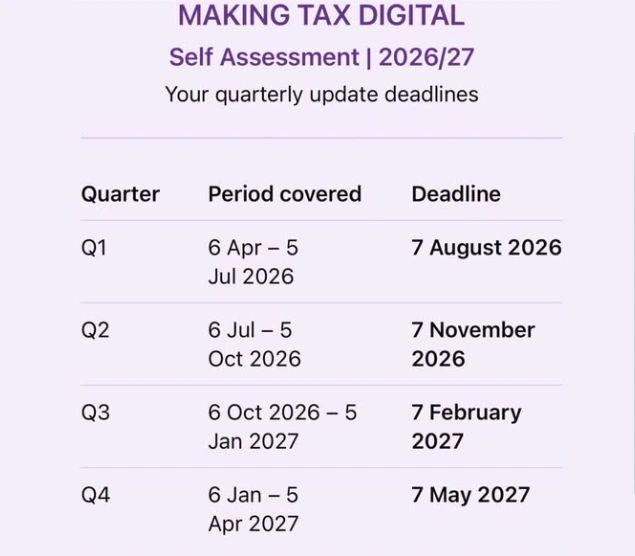
Making Tax Digital Deadlines 2026/27
Making Tax Digital (MTD) for income tax came into force for landlords and sole traders from 2026/27.
In addition to the self assessment deadlines above, those who are captured by the MTD deadlines have the following quarterly deadlines to follow.
Sole traders and landlords with combined rental and trading income of £50,000 will have to register for MTD for 2026/27. More information on this is given at our dedicated MTD page..
Experienced professionals dedicated to your success.
Proven results that speak for themselves.
Disclaimer
Why Work With Us
Personalized service tailored to your unique needs.
Experienced professionals dedicated to your success.
Proven results that speak for themselves.
